


The demand for bank loans to purchase a home, buy a car, invest in a business or supplement working capital continues to increase. However, many borrowers face loan rejection or lengthy application processing because they do not clearly understand what do you need to apply for a bank loan, what eligibility requirements must be met and how banks assess a loan application.
In practice, loan approval depends on more than just income. Banks also consider the borrower’s credit history, loan purpose, repayment capacity and, particularly for secured loans, the value of the collateral. The following article provides a comprehensive overview of the required documents, eligibility criteria and practical considerations for applying for a bank loan effectively in 2026.
What is a bank loan?
A bank loan is a form of financing in which a customer receives a sum of money from a bank and is obligated to repay both principal and interest within the timeframe agreed in the credit contract.
Banks in Vietnam currently offer a range of different loan products such as:
-
Home loans.
-
Auto loans.
-
Consumer loans.
-
Business production loans.
-
Secured (mortgage) loans.
-
Unsecured loans based on salary.
-
Business working-capital loans.
-
Project investment loans.
Each product has its own documentation requirements and approval conditions.
What do you need for a bank loan?
To be considered for credit, a customer generally needs to meet the following groups of conditions at the same time:
Have complete personal identification documents
This document set is mandatory for every loan.
It typically includes:
-
A valid citizen ID card or ID card.
-
Residence confirmation or electronic residence information.
-
A marriage certificate or a certificate of single status.
-
A passport (if available).
Banks use this documentation to verify identity and assess the borrowers legal standing.
Have a stable source of income
Income is a key factor banks use to assess repayment capacity.
The types of documents typically required include:
For salaried employees
-
Labor contract.
-
Appointment decision (if applicable).
-
Salary statements for the most recent 3–12 months.
-
Employment confirmation.
For household businesses
-
Business license.
-
Sales records.
-
Input and output invoices.
-
Business account statements.
For companies
-
Financial statements.
-
Tax declarations.
-
Economic contracts.
-
Corporate legal documentation.
The more stable the income, the higher the likelihood of loan approval.
Have a good credit history
The bank will check a customers credit information through the CIC system.
Cases that commonly run into difficulty securing a loan include:
-
Having bad debt in group 3, 4 or 5.
-
Repeated late payments.
-
An excessively large outstanding credit balance.
-
A history of overdue guaranteed debt.
Before applying for a loan, customers should check their CIC status to proactively address any issues.
Have a clear loan purpose
The bank needs to know what the loan amount will be used for.
Some of the documents used to demonstrate loan purpose include:
-
A property sale-and-purchase contract.
-
A car purchase contract.
-
A construction or renovation contract.
-
A business plan.
-
An investment contract.
A transparent loan purpose helps the appraisal process move faster.
What does a bank loan application include?
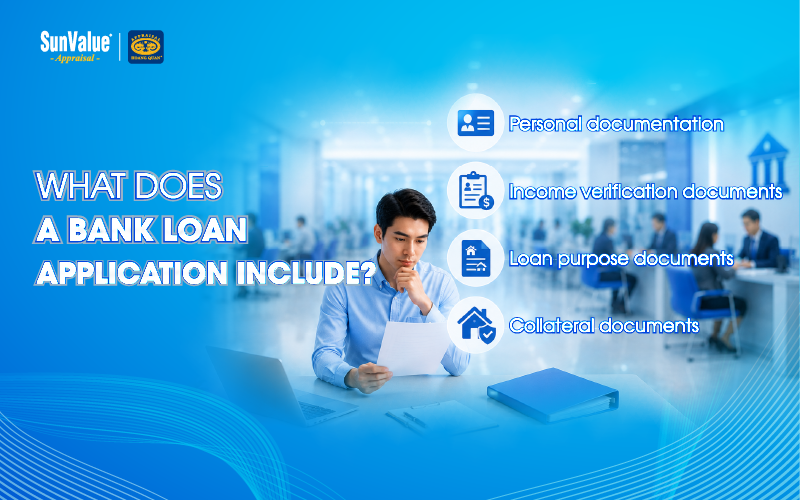
Personal documentation
-
Citizen ID card or ID card.
-
Residence confirmation.
-
Marriage certificate or certificate of single status.
Income verification documents
-
Salary statements.
-
Labor contract.
-
Business license.
-
Financial statements.
Loan purpose documents
-
Sale-and-purchase contract.
-
Asset quotation.
-
Fund-use plan.
Collateral documents
For a secured (mortgage) loan customers need to prepare:
-
Land use right certificate.
-
House ownership certificate.
-
Vehicle registration certificate.
-
Savings book.
-
Machinery and equipment.
-
Factory buildings.
-
Warehouses.
-
Assets to be formed in the future.
The current bank loan process
Step 1 – Prepare documentation: The customer prepares all the paperwork required by the bank.
Step 2 – Submit the application: The bank receives and checks the validity of the documents.
Step 3 – Customer appraisal: The bank assesses:
-
Financial capacity.
-
Income.
-
Credit history.
-
Intended use of funds.
Step 4 – Collateral appraisal: This step is especially important for secured loans. The bank or an independent appraisal provider determines the actual value of the asset.
Step 5 – Loan approval: After completing the appraisal the bank decides on the credit limit and loan term.
Step 6 – Sign the contract and disburse funds: The customer signs the credit documents and receives the loan amount.
Is an appraisal mandatory for a bank loan?
This is a question many customers ask when preparing to apply for a loan.
The answer is that not every loan requires an asset appraisal, but most high-value loans do go through an appraisal process before disbursement.
Banks generally apply two main types of loans:
Unsecured loans (no asset appraisal required)
This is a type of loan based on:
-
Personal credit standing.
-
Monthly income.
-
Labor contract.
-
Repayment history.
The borrower does not need to mortgage an asset such as real estate or a car.
Advantages:
-
Simple documentation.
-
Fast approval time.
-
Funds can be disbursed within 1–3 days.
Limitations:
-
Lower loan limits.
-
Higher interest rates than secured loans.
-
Fairly strict income-approval conditions.
Unsecured loans typically range from tens of millions to a few hundred million VND depending on the bank.
Secured (mortgage) loans (asset appraisal required)
This is a common type of loan for:
-
Buying a house.
-
Buying land.
-
Buying a car.
-
Topping up business capital.
-
Project investment.
-
Business loans.
The bank will require the customer to provide collateral and will carry out an appraisal before deciding on the loan limit.
Advantages:
-
Higher loan limits.
-
Longer loan terms.
-
Lower interest rates than unsecured loans.
For loans ranging from a few hundred million to tens of billions of VND, the asset appraisal result is typically a critical basis for the banks credit decision.
Why must banks appraise an asset before lending?
Many customers assume that once a property has a legal certificate, the bank will lend based on the market price.
In practice, however, this is not the case.
The bank needs an appraisal to determine:
-
The assets actual market value.
-
The assets legal status.
-
Its liquidity.
-
The level of risk involved in extending credit.
Example:
A homeowner may believe their house is worth around 6 billion VND, but after reviewing the location, legal status, planning and transactions in the area, the value accepted by the bank may only be around 4.8–5.2 billion VND.
This directly affects the loan limit the customer is granted.
Why do many loan applications get rejected?
Even with a legitimate need for financing, many customers still get turned down. The common causes include:
-
Incomplete documentation: Missing paperwork or an invalid application.
-
Income that doesnt meet requirements: Unable to demonstrate a stable source of repayment.
-
Bad debt on the CIC system: This is the most common reason applications get rejected.
-
Collateral of insufficient value: The assets value is lower than the loan amount requested.
-
Assets with legal issues, for example:
-
Land under dispute.
-
A house without as-built certification.
-
Land subject to planning restrictions.
-
Assets not yet eligible for transactions.
-
The role of asset appraisal in securing a bank loan
For secured loans, the value of the collateral is the basis the bank uses to determine the credit limit.
Banks typically lend between 60% and 85% of the assets appraised value.
Example:
If a house is appraised at:
-
2 billion VND → the loan limit is roughly 1.2–1.7 billion VND.
-
5 billion VND → the loan limit is roughly 3–4.25 billion VND.
As a result, the appraisal outcome has a direct impact on the customers ability to access capital.
An accurate, objective and market-appropriate appraisal report helps:
-
Optimize the loan limit.
-
Shorten the approval time.
-
Increase the transparency of the application.
-
Limit legal risk.
-
Support more effective negotiation with the bank.
Hoang Quan Appraisal supports collateral appraisal for bank loans
During the loan process many customers focus only on the interest rate and overlook the fact that the value of the collateral is what directly determines the credit limit granted.
With many years of experience appraising assets and collateral for banks, credit institutions and businesses nationwide, Hoang Quan Appraisal supports customers with:
-
Residential land appraisal.
-
Apartment appraisal.
-
Machinery and equipment appraisal.
-
Vehicle appraisal.
-
Loan collateral appraisal.
Benefits of choosing Hoang Quan Appraisal:
-
A team of highly qualified valuers.
-
An extensive market-price data system.
-
A transparent process that complies with the law.
-
Support with loan applications at multiple banks, improving the chance of bank approval.
-
Shorter approval and disbursement times.
-
Appraisal reports with legal validity as required by regulation.
-
A clear understanding of the assets actual market value.
-
The ability to proactively calculate the loan limit.
-
Support in building a more effective credit application.
Getting an accurate asset valuation not only helps customers access capital more easily but also builds a solid financial foundation for future plans such as buying a home, expanding production and business or investing.
Are you preparing to apply for a home loan, a business loan or a secured loan?
Dont wait until the bank values your asset to find out how much you can borrow.
Contact Hoang Quan Appraisal to determine your collaterals value from the very start, proactively plan your finances, optimize your credit limit and increase your chances of bank approval.
Accurate valuation - Proactive financing - Greater chance of success.
Hoang Quan Appraisal Company Limited
Address: Hoang Quan Appraisal System
Phone number: 0934.252.707
Email: contact@sunvalue.vn
Facebook: Hoang Quan Appraisal
Website: hqa.com.vn
Tips to get your loan application approved faster
To improve your chances of bank approval, customers should:
- Prepare complete documentation from the start:
-
Personal documentation.
-
Income documentation.
-
Loan purpose documentation.
-
Collateral documentation.
-
- Maintain a good credit history:
-
Avoid overdue debt.
-
Pay existing loans on time.
-
Check your CIC status before submitting an application.
-
-
Clearly demonstrate your source of income.
-
Avoid overdue debt before applying for a loan.
-
Choose a loan limit that matches your repayment capacity.
-
Proactively appraise your collateral before submitting an application.
-
Work with a reputable appraisal provider.
Frequently asked questions
-
What documents do I need for a bank loan?
Typically these include a citizen ID card, residence confirmation, income verification documents, loan purpose documents and collateral documents if applying for a secured loan.
-
Can I still get a bank loan if I have bad debt?
Customers with bad debt in group 3, 4 or 5 usually find it very difficult to get a loan approved by a bank.
-
Do I need to provide collateral for a bank loan?
Not necessarily. Unsecured loans dont require collateral, but secured loans generally offer lower interest rates and higher limits.
-
What is the maximum percentage of an assets value that a bank will lend?
Typically between 60% and 85% of the appraised value.
-
Is an asset appraisal mandatory for a secured loan?
Most secured loans require an asset appraisal to determine the collateral value and an appropriate credit limit.
-
Should I get an asset appraisal before applying for a loan?
Yes. Doing so helps you know your borrowing capacity in advance, plan your finances proactively and shorten the application review time.
Conclusion
Getting a bank loan isnt as simple as submitting an application and waiting for disbursement. To get approved quickly, customers need to fully meet the requirements around personal identity, income, credit history, loan purpose and collateral. Among these, the value of the mortgaged asset is one of the most important factors determining the loan limit.
If youre preparing an application for a home loan, a business loan or a secured loan, getting an appraisal from the very start will help you proactively determine your assets value, optimize your credit limit and increase your chances of bank approval. Hoang Quan Appraisal is ready to accompany you throughout the process of building a professional, transparent and effective loan application.


